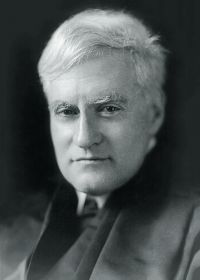
 Benjamin N. Cardozo,
Baltimore National Bank v. State Tax Commission of Maryland…
“ Maryland, 4 Wheat. 316, 4 L.Ed. 579, a corporation so conceived and operated is an instrumentality of government without distinction in that regard between one activity and another. Even on that assumption taxation by state or municipality may overpass the usual limits if the consent of the United States has removed the barriers or lowered them.We think consent has been so given where shares in a national bank are the property to be taxed, though an agency of government is the owner of the assets subjected to the burden. ”
