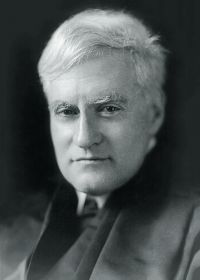
 Benjamin N. Cardozo,
Clifton Manufacturing Co. v. United States…
“ A deficiency assessment was imposed in May, 1921, which is admitted to have been timely, and another on May 26, 1926, which is contested as too late. There is also a contest in respect of both deficiencies growing out of delay in the collection. True, written waivers were in existence, adequate in form, which extended the date for assessment and collection until December 31, 1926. The taxpayer asserts, however, that they were procured by misrepresentation and signed without authority, and must therefore be ignored. ”
