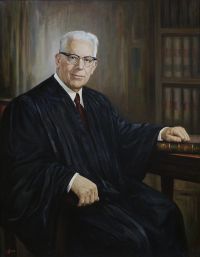
 Earl Warren,
Fribourg Navigation Company v. Commissioner of Internal Revenue…
“ In Massey and Hertz we held that when a taxpayer, at the time he acquires an asset, reasonably expects he will use it for less than its full physical or economic life, he must, for purposes of computing depreciation, employ a useful life based on the period of expected use. We recognized in those cases that depreciation is based on estimates as to useful life and salvage value. ”
