Summary

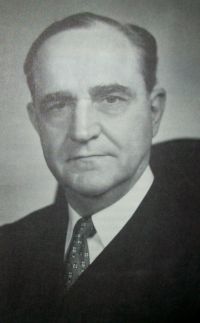
Portrait of Sherman Minton Sherman Minton United States v. Gilbert Associates…

A cardinal principle of Congress in its tax scheme is uniformity, as far as may be. Therefore, a 'judgment creditor' should have the same application in all the states. In this instance, we think Congress used the words 'judgment creditor' in § 3672 in the usual, conventional sense of a judgment of a court of record, since all states have such courts.
Source: Wikisource

Portrait of Sherman Minton Sherman Minton United States v. Gilbert Associates…

In the office of the clerk of the United States district court for the judicial district in which the property subject to the lien is situated * * *.' The Supreme Court of New Hampshire held that since notice of the Government's lien was not filed until August 6, 1948, and the Town's taxes were assessed on April 1, 1947, and April 1, 1948, respectively, and such tax assessments are 'in the nature of a judgment' under the law of New Hampshire, the Town was a judgment creditor within the meaning of § 3672, and the Government's lien was not valid as against the Town's.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature