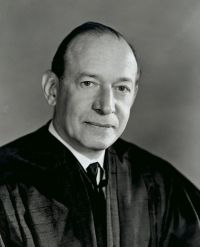
 Abe Fortas,
Commissioner of Internal Revenue v…
“ As my Brother HARLAN states, in a case in which federal tax consequences depend upon state property interests, a federal court should accept the final conclusion of a competent state court, assuming that such a conclusion is an adjudication of substance arrived at after adversary litigation and on the basis of the same careful consideration that state courts normally accord cases involving the determination of state property interests. ”
