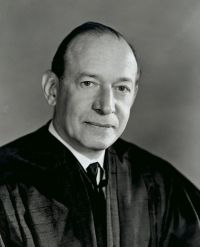
 Abe Fortas,
Dunban-Stanley Studios, Inc. v…
“ In determining whether a state tax imposes an impermissible burden on interstate commerce, the issue is whether the local activity which is made the nominal subject of the tax is 'such an integral part of the interstate process, the flow of commerce, that it cannot realistically be separated from it.' Michigan-Wisconsin Pipe Line Co. ”
