Summary

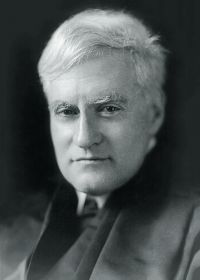
Portrait of Benjamin N. Cardozo Benjamin N. Cardozo National Paper Products Co. v. Helvering Zellerbach Paper Co…

The tax payable by the petitioners for the preceding fiscal year was changed by the new act in one respect only. For the four months of that year following January 1, 1925, the 12 1/2 per cent. tax fixed by the Act of 1924 was increased to 13 per cent. (Section 230 (a) (1) , 26 USCA § 981 note) , an amount ascertainable through a simple computation when once the data had been supplied for separating income attributable to 1925 from income attributable to an earlier time. For other taxpayers differently situated, the changes might be different or greater.
Source: Wikisource

Portrait of Benjamin N. Cardozo Benjamin N. Cardozo National Paper Products Co. v. Helvering Zellerbach Paper Co…

Here, on July 15, 1925, the Zellerbach Paper Company filed for itself and its subsidiary, National Paper Products Company, a consolidated return under the Revenue Act of 1924 (43 Stat. 253) for the fiscal year ending April 30, 1925.
On February 26, 1926, the Revenue Act of 1926 (44 Stat. 9) was enacted, effective retroactively in respect of income taxes (with exceptions not now important) as of January 1, 1925. Sections 286, 1200 (26 USCA §§ 931 note, 1a note, 1260a) .
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature