Summary

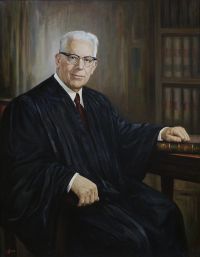
Portrait of Earl Warren Earl Warren United States v. Manufacturers National Bank of Detroit…

The maturing of the right to proceeds is therefore an appropriate occasion for taxing the transaction to the estate of the insured. Cf. Tyler v. United States, 281 U.S. 497, 503, 504, 50 S.Ct. 356, 359.
There is no inconsistency between such a view of the taxable event and the basic definition of the subject of the tax in Section 810. 'Obviously, the word 'transfer' in the statute, or the privilege which may constitutionally be taxed, cannot be taken in such a restricted sense as to refer only to the passing of particular items of property directly from the decedent to the transferee.
Source: Wikisource

Portrait of Earl Warren Earl Warren United States v. Manufacturers National Bank of Detroit…

The taxpayer is his executor. On the estate tax return, the taxpayer included, as part of the gross estate, the proceeds of four insurance policies payable to the wife of the insured. These policies were originally issued to the insured, but he divested himself of the policy rights by assigning them to his wife on December 18, 1936. However, he continued to pay the premiums on the policies until he died. After his death, the proceeds were retained by the insurer for the benefit of the family, pursuant to the provisions of a settlement option selected by the wife.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature