Summary

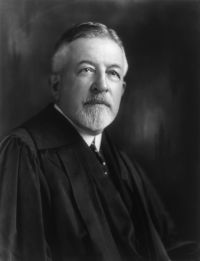
Portrait of Edward Terry Sanford Edward Terry Sanford Hellmich v. Hellman — Opinion of the Court

It is true that if section 201 (a) stood alone its broad definition of the term 'dividend' would apparently include distributions made to stockholders in the liquidation of a corporation-although this term, as generally understood and used, refers to the recurrent return upon stock paid to stockholders by a going corporation in the ordinary course of business, which does not reduce their stock holdings and leaves them in a position to enjoy future returns upon the same stock.
Source: Wikisource

Portrait of Edward Terry Sanford Edward Terry Sanford Hellmich v. Hellman — Opinion of the Court

However, if such stock was acquired prior to March 1, 1913, and the fair market value as of such date was greater than the cost but less than the amount so distributed, the taxable income is the excess over such fair market value of the amount received, but no gain is recognized if the amount received, although more than cost, is less than the fair market value of the stock on March 1, 1913.' 23 Treas.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature