Summary

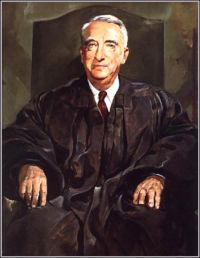
Portrait of Fred M. Vinson Fred M. Vinson McWilliams v. Commissioner of Internal Revenue…

Even assuming that the problem was thought to arise solely out of the taxpayer's inherent advantage in a contest concerning the good or bad faith of an intra-family sale, deception could obviously be practiced by a buying spouse's agreement or tacit readiness to hold the property sold at the disposal of a selling spouse, rather more easily than by a pretense of a sale where none actually occurred, or by an unfair price.
Source: Wikisource

Portrait of Fred M. Vinson Fred M. Vinson McWilliams v. Commissioner of Internal Revenue…

Nor can we agree that Congress' omission from § 24 [b] of any prescribed time interval, comparable in function to that in the wash sales provisions, indicates that § 24 (b) was not intended to apply to intra-family transfers through the Exchange. Petitioners' argument is predicated on the difficulty which courts may have in determining whether the elapse of certain periods of time between one spouse's sale and the other's purchase of like securities on the Exchange is of great enough importance in itself to break the continuity of the investment and make § 24 (b) inapplicable.
Source: Wikisource

Portrait of Fred M. Vinson Fred M. Vinson McWilliams v. Commissioner of Internal Revenue…

Petitioners also urge that, whatever may have been Congress' intent, its designation in § 24 (b) of sales 'between' members of a family is not adequate to comprehend the transactions in this case, which consisted only of a sale of stock by one of the petitioners to an unknown stranger, and the purchase of different certificates of stock by the other petitioner, presumably from another stranger.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature