Summary

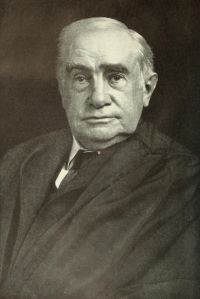
Portrait of Henry Billings Brown Henry Billings Brown Snyder v. Bettman — Opinion of the Court

If it be true that the right to impose such taxes arises solely from the right to regulate successions, then a denial of such right goes to the whole power of the government to impose a succession tax, irrespective of the question whether the legacy is made to a private individual or to an agent of the state, and the cases in this court upholding the power of the Federal government to lay such tax were wrongly decided.
Source: Wikisource

Portrait of Henry Billings Brown Henry Billings Brown Snyder v. Bettman — Opinion of the Court

If the position of the plaintiff be sound, it will come to pass that, with the same power to tax the subject-matter, i. e., the transmission of the property, the states are competent to limit the amount of bequests to the Federal government by requiring the prepayment of a succession tax as a condition precedent to the transmission of the property, while Congress is impotent to accomplish complish the same result with respect to legacies to states or their agents. We are reluctant to admit the inferiority of Congress in that particular.
Source: Wikisource

Portrait of Henry Billings Brown Henry Billings Brown Snyder v. Bettman — Opinion of the Court

This case must be regarded as definitely establishing the doctrine that the power to tax inheritances does not arise solely from the power to regulate the descent of property, but from the general authority to impose taxes upon all property within the jurisdiction of the taxing power. It has usually happened that the power has been exercised by the same government which regulates the succession to the property taxed
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature