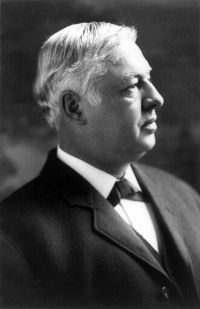
 Joseph Rucker Lamar,
Downman v. Texas — Opinion of the Court
“ The Texas court recognized that if a mineral right was not an estate, but a mere license to enter and work in the future, it was not taxable. It held, however, that the deeds conveying ore, store, and minerals were grants of property, and conveyed to Downman title to the mineral, with the right to work the same. This title and right were held to be real estate, and taxable as such. ”
