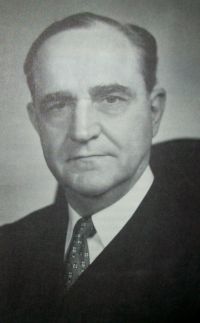
 Sherman Minton,
United States v. Acri — Opinion of the Court
“ We held that although New Hampshire might treat its tax assessments as judgments for state purposes, the assessment of the tax was not a judgment within the meaning of § 3672. We hold here that the attachment lien in Ohio is for federal tax purposes an inchoate lien because, at the time the attachment issued, the fact and the amount of the lien were contingent upon the outcome of the suit for damages. ”
