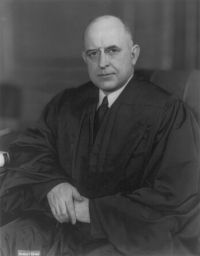
 Stanley Forman Reed,
Squire v. Capoeman — Dissent
“ My view is that the sale price of the timber in excess of its market value on March 1, 1913, was a capital gain, subject to federal income tax. Jones v. Taunah, 10 Cir., 186 F.2d 445. Cf. Choteau v. Burnet, 283 U.S. 691, 51 S.Ct. 598, 75 L.Ed. 1353; Superintendent of Five Civilized Tribes, etc. v. Commissioner of Internal Revenue, 295 U.S. 418, 55 S.Ct. 820, 79 L.Ed. 1517. The gain is taxable income like the value of annual crops. ”
