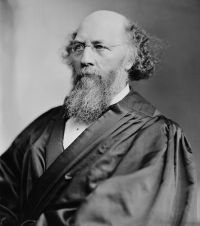
 Stephen Johnson Field,
United States v. Cooper — Opinion of the Court
“ The thirty-sixth section of the act of August 5, 1861, in prescribing the manner in which property subject to a direct tax shall be sold, where it is not divisible, so that by a sale of a part the whole amount of the tax, with costs, charges, and commissions, may be raised, provides that 'the surplus of the proceeds of the sale, after satisfying the tax, costs, charges, and commissions, shall be paid to the owner of the property, or his legal representatives ”
