Summary

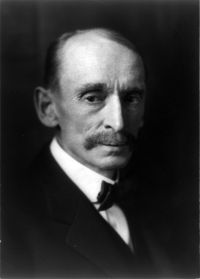
Portrait of William R. Day William R. Day New York ex rel. Edward and John Burke Limited v…

Maryland recognizes that the importer may lose this right of protection by mingling such goods with other property, and altering their character as importations in original packages, and making them by his conduct subject to the taxing power of the state. And we think the same principle may be applied to the proceeds of the sale of the goods, which, while not directly taxable as such, any more than the goods themselves, may be dealt with by the owner in such wise as to become subject to taxation as other property.
Source: Wikisource

Portrait of William R. Day William R. Day New York ex rel. Edward and John Burke Limited v…

Rep. 365, the distinction was pointed out between taxes upon goods imported from abroad-imported in the legal sense-and those sent from another state; as to which latter class of merchandise the states have the power, after the goods reach their destination and are held for sale, to tax them. Whereas, following Brown v. Maryland, where goods are imported in the strict sense, they preserve their character as imports so long as they are not sold in the original packages in which they are imported, or by the act of the importer incorporated into the general property of the state.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature