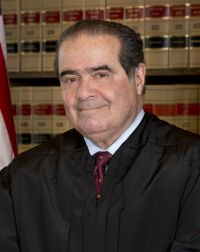
 Antonin Scalia,
Trinova Corporation v. Michigan Department of Treasury…
“ As a practical matter, Michigan's SBT is nothing more than an amalgam of three separate taxes: a tax on payroll, a tax on depreciable fixed assets, and a tax on income. Payroll and depreciation represent over 90 percent of the SBT base, and the productive activities that are measured by payroll and depreciation take place at geographic locations that are readily identifiable. ”
