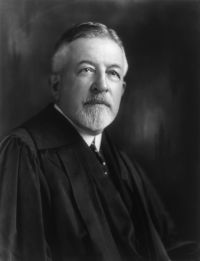
 Edward Terry Sanford,
American National Company v. United States…
“ The Company's net income for the year could not have been rightly determined without deducting from the gross income represented by the commission notes, the obligations which it incurred under the bonus contracts, and would not have been accurately shown by keeping its books or making its return on the basis of actual receipts and disbursements. The method which it adopted clearly reflected the true income. ”
