Summary

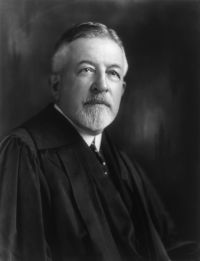
Portrait of Edward Terry Sanford Edward Terry Sanford Gorham Manufacturing Company v…

That a State cannot constitutionally levy a tax computed on an allocated part of the total net income of a foreign corporation, where the allocation includes certain arbitrarily selected factors, none of which are determinative of net income, and omits other factors equally important, and the result is to allot more income to the State than was earned there and employ income totally unrelated thereto to enlarge the measure of the tax
Source: Wikisource

Portrait of Edward Terry Sanford Edward Terry Sanford Gorham Manufacturing Company v…

The Company insists that the inclusion in the net income upon which the tax was based of the income derived from business not carried on in New York, in the manufacture and sale of munitions and the manufacture of ware, and the allocation of that net income to New York by the statutory ratio into which only certain assets entered, has resulted in an assessment against it of a tax based upon an allocated income greatly in excess of that in fact derived from the business of selling ware which it carried on within the State.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature