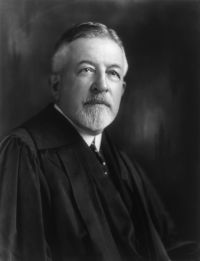
 Edward Terry Sanford,
McCaughn v. Ludington — Opinion of the Court
“ Flannery, is a substantial transcript of the Revenue Act of 1918, except that January 1, 1919, is substituted for March 1, 1913, it was specifically held, in a case precisely similar to the present, that the loss deductible by the taxpayer was limited to the difference between the purchase and selling prices, although on January 1, 1919, the property had a higher value than when it was purchased, and the loss if computed from that date would have been greater than when computed from the purchase price. People ex rel. ”
