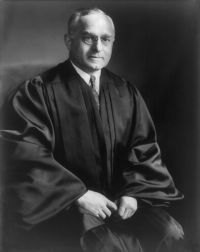
 Felix Frankfurter,
Bazley v. Commissioner of Internal Revenue…
“ One does not have to pursue the motives behind actions, even in the more ascertainable forms of purpose, to find, as did the Tax Court, that the whole arrangement took this form instead of an outright distribution of cash or debentures, because the latter would undoubtedly have been taxable income whereas what was done could, with a show of reason, claim the sheller of the immunity of a recapitalization-reorganization. ”
