Summary

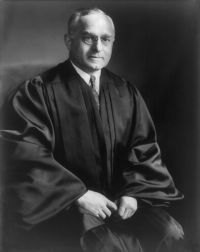
Portrait of Felix Frankfurter Felix Frankfurter Commissioner of Internal Revenue v…

Treating the matter as a problem of statutory construction for our independent judgment, we hold that a distribution, pursuant to a reorganization, of earnings and profits 'has the effect of the distribution of a taxable dividend' within § 112 (c) (2) . As is true of other teasing questions of construction raised by technical provisions of Revenue Acts the matter is not wholly free from doubt. But these doubts would have to be stronger than they are to displace the informed views of the Tax Court.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Commissioner of Internal Revenue v…

Whether the announcement of an opinion and its entry in the docket amounts to a judgment for purposes of appeal or whether that must await some later formal act, ought not to be decided on nice-spun argumentation in disregard of the judicial habits of the court whose judgment is called into question, of the bar practising before it, of the clerk who embodies its procedural traditions, as well as in conflict with the assumption of the reviewing court.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Commissioner of Internal Revenue v…

The normal time for entering a judgment, as the starting point for determining whether review will be sought or whether there has been acquiescence in a judgment, should be fixed. The uncertainties inherent in litigation should not be needlessly prolonged. The entry of the 'Order for Mandate', which in the Second Circuit begins the running of the period for appeal, is apparently variable and vagrant.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature