Summary

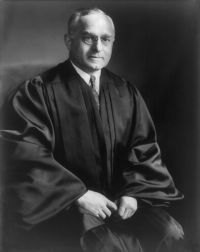
Portrait of Felix Frankfurter Felix Frankfurter Freeman v. Hewit — Dissent

It is not a tax on interstate selling. The tax is on the proceeds of the sales less the brokerage commissions and therefore does not reach the revenues from the only interstate activities involved in these transactions. It is therefore essentially no different, so far as the Commerce Clause is concerned from a tax by Indiana on the proceeds of the sale of a farm or other property in New York where the mails are used to authorize it, to transmit the deed, and to receive the proceeds.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Freeman v. Hewit — Dissent

The management of an investment portfolio with income from out-of-state sources is as much a local activity as the manufacture of goods destined for interstate commerce, American Mfg. Co. v. City of St. Louis, supra, the publication of a trade journal with interstate revenues, Western Live Stock v. Bureau of Revenue, supra, or the growing of fruit for interstate markets, Gwin, White & Prince Inc. v. Henneford, supra. All such taxes affect in some measure interstate commerce or increase the cost, of doing it.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature