Summary

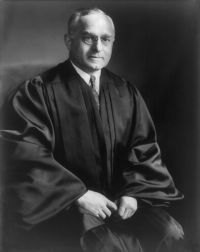
Portrait of Felix Frankfurter Felix Frankfurter General Trading Company v. State Tax Commission of Iowa…

The tax is what it professes to be-a non-discriminatory excise laid on all personal property consumed in Iowa. The property is enjoyed by an Iowa resident partly because the opportunity is given by Iowa to enjoy property no matter whence acquired. The exaction is made against the ultimate consumer-the Iowa resident who is paying taxes to sustain his own state government. To make the distributor the tax collector for the State is a familiar and sanctioned device.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter General Trading Company v. State Tax Commission of Iowa…

From Minnesota it ships goods ordered from salesmen by purchasers in Iowa. Orders are accepted only in Minnesota. The transaction of sale is not taxed and, being clearly interstate commerce, is not taxable. McLeod v. Dilworth Co., 322 U.S. 327, 64 S.Ct. 1023. So we are holding that a state has power to make a tax collector of one whom it has no power to tax. Certainly no state has a constitutional warrant for making a tax collector of one as the price of the privilege of doing interstate commerce. He does not get the right from the state, and the state cannot qualify it.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature