Summary

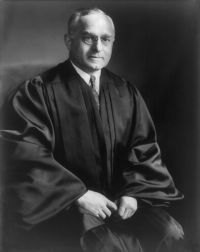
Portrait of Felix Frankfurter Felix Frankfurter McLeod v. J. E. Dilworth Company…

Whatever might be the fate of such a tax were it before us, the not too short answer is that Arkansas has chosen not to impose such a use tax, as its Supreme Court so emphatically found. A sale tax and a use tax in many instances may bring about the same result. But they are different in conception, are assessments upon different transactions, and in the interlacings of the two legislative authorities within our federation may have to justify themselves on different constitutional grounds. A sales tax is a tax on the freedom of purchase-a freedom which wartime restrictions serve to emphasize.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter McLeod v. J. E. Dilworth Company…

A use tax is a tax on the enjoyment of that which was purchased. In view of the differences in the basis of these two taxes and the differences in the relation of the taxing state to them, a tax on an interstate sale like the one before us and unlike the tax on the enjoyment of the goods sold, involves an assumption of power by a State which the Commerce Clause was meant to end.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter McLeod v. J. E. Dilworth Company…

We are asked to reverse a decision of the Supreme Court of Arkansas holding that the Commerce Clause precludes liability for the sales tax of that State upon the transactions to be set forth.
We take the descriptions of these transactions from the opinion under review. Respondents are Tennessee corporations with home offices and places of business in Memphis where they sell machinery and mill supplies. They are not qualified to do business in Arkansas and have neither sales office, branch plant nor any other place of business in that State.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature