Summary

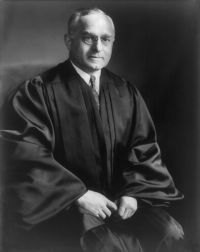
Portrait of Felix Frankfurter Felix Frankfurter Griffiths v. Helvering — Opinion of the Court

The facts are undisputed, and, for purposes of our decision, may be thus abridged: In 1926 Griffiths, the petitioner, paid one Lay $100,000 for some stock. The investment was unprofitable, and the upshot of a complicated series of transactions was allowance to Griffiths by the Commissioner of a deductible loss of $92,500 for the year 1931 resulting from a sale of the stock by Griffiths to a family corporation. Thereafter, in 1932, Griffiths got wind of the fact that Lay had defrauded him in the 1926 sale.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Griffiths v. Helvering — Opinion of the Court

Helvering, 302 U.S. 609, 613, 58 S.Ct. 393, 395, 82 L.Ed. 474, 'is not made a different result because reached by following a devious path.' Legislative words are not inert, and derive vitality from the obvious purposes at which they are aimed, particularly in the provisions of a tax law like those governing installment sales in § 44 of the Revenue Act of 1932. Taxes cannot be escaped 'by anticipatory arrangements and contracts however skilfully devised * * * by which the fruits are attributed to a different tree from that on which they grew.' Lucas v.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature