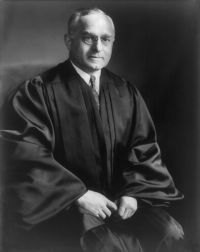
 Felix Frankfurter,
Merrill v. Fahs — Opinion of the Court
“ It seems to us clear that with the judicial history of the difficulties in estate and gift taxes as to the transfer of marital rights, when Congress expressly provided that relinquishment of dower, curtesy or other statutory estate was not 'consideration' for estate tax purposes and left the gift tax provision without such a limitation, it intended that these rights be accorded a different treatment under these sections. ”
