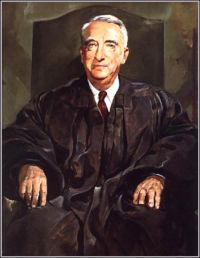
 Fred M. Vinson,
Crane v. Commissioner of Internal Revenue…
“ Or put in another way, we are no more concerned with whether the mortgagor is, strictly speaking, a debtor on the mortgage, than we are with whether the benefit to him is, strictly speaking, a receipt of money or property. We are rather concerned with the reality that an owner of property, mortgaged at a figure less than that at which the property will sell, must and will treat the conditions of the mortgage exactly as if they were his personal obligations. ”
