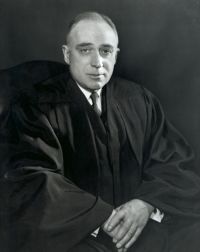
 John Marshall Harlan II,
Commissioner of Internal Revenue v…
“ Long-established principles govern the application of the more favorable tax rates to long-term capital gains: (1) There must be first, a 'capital asset,' and second, a 'sale or exchange' of that asset (§ 117 (a) ) ; (2) 'capital asset' is defined as 'property held by the taxpayer,' with certain exceptions not here relevant (§ 117 (a) (1) ) ”