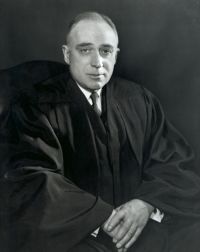
 John Marshall Harlan II,
Commissioner of Internal Revenue v…
“ This Court has long held that the term 'capital asset' is to be construed narrowly in accordance with the purpose of Congress to afford capital-gains treatment only in situations typically involving the realization of appreciation in value accrued over a substantial period of time, and thus to ameliorate the hardship of taxation of the entire gain in one year. ”
