Summary

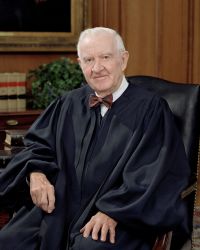
Portrait of John Paul Stevens John Paul Stevens,  California State Board of Equalization v…

“ It is evident that whatever immunity the bankruptcy estate once enjoyed from taxation on its operations has long since eroded and that there is now no constitutional impediment to the imposition of a sales tax or use tax on a liquidation sale. There is no claim, nor could there be, that the tax discriminates against bankruptcy trustees or those with whom they deal. ”
Source: Wikisource

Portrait of John Paul Stevens John Paul Stevens,  California State Board of Equalization v…

“ See Wurzel, Taxation During Bankruptcy Liquidation, 55 Harv.L.Rev. 1141, 1166-1169 (1942) (footnote omitted) (" [T] here is no implied immunity of a federal instrumentality from a state tax that is general and nondiscriminatory if its effects upon the Federal Government are merely 'incidental.' A general and nondiscriminatory tax on a trustee fulfills this requirement. . . . The tax does not place a financial burden upon the United States; nor will it-unless it is discriminatory and therefore unconstitutional-render the trustee's task more difficult or cumbersome") ”
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature