Summary

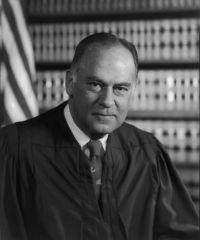
Portrait of Potter Stewart Potter Stewart Schlude v. Commissioner of Internal Revenue…

Whatever other artificialities the exigencies of revenue collection may require in the field of tax accounting, it has never before today been suggested that a consistent method of accrual accounting, valid for purposes of recognizing income, is not equally valid for purposes of deferring income. Yet in this case the Court says that the taxpayers, in recognizing income, should have used the very system of statistical estimates which, for income deferral purposes, the American Automobile decision held impermissible.
Source: Wikisource

Portrait of Potter Stewart Potter Stewart Schlude v. Commissioner of Internal Revenue…

The most elementary principles of accrual accounting require that advances be considered reportable income only in the year they are earned by the taxpayer's rendition of the services for which the payments were made. The Government's theories would force upon an accrualbasis taxpayer a cash basis for advance payments in disregard of the federal statute which explicitly authorizes income tax returns to be based upon sound accrual accounting methods.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature