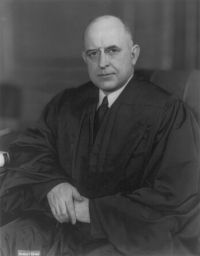
 Stanley Forman Reed,
Best Company v. Maxwell — Opinion of the Court
“ The retail stores of the state are the natural outlets for merchandise, not those who sell only by sample. Some of these local shops may, like appellant, rent temporary display rooms in sections of North Carolina where they have no permanent store, but even these escape the tax at bar because the location of their central retail store somewhere within the state will qualify them as 'regular retail merchants in the State of North Carolina.' The only corresponding fixed-sum license tax to which appellant's real competitors are subject is a tax of $1 per annum for the privilege of doing business. ”
