Summary

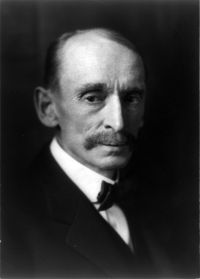
Portrait of William R. Day William R. Day United States v. Biwabik Mining Company…

The contract was a 'lease,' the receipts were 'royalties,' and royalties, being rentals, are inherently income and have been commonly so considered. All these things seem to have affected the conclusion of the court, but, after all the dominating thought appears to be that, when land is devoted to mining it is put to only one of those productive uses of which it is capable, and that the product of the use should be called income. The land itself is the chief thing. After the mining is finished the land remains suitable for other uses
Source: Wikisource

Portrait of William R. Day William R. Day United States v. Biwabik Mining Company…

These reasons do not apply at all to the case of the lessee whose existing interest, at the beginning of the taxing period, over and above the royalty which he must pay, amounted to $3,000,000; his entire interest was each year, as far as he went, consumed and exhausted forever; he did not have remaining the principal thing, the land, which he could put to some other use; the receipt in 1910 of his January 1, 1909, interest in the ore was not the offshoot and income of his property
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature