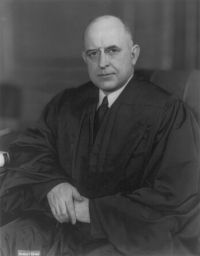
 Stanley Forman Reed,
Douglas v. Commissioner of Internal Revenue…
“ On the contrary, it perverts recoupment by pyramiding income spread in receipt over many years into 'income' received in a single, entirely different one. And in a day when the tax rate mounts more often than yearly the skyrocketing effect of the process operates with wholly incalculable effect on the taxpayer, who it will be noted has no control over the contingency which brings it into play.A regulation which would require the taxpayer to pay the taxes deducted for the prior years together with the usual interest and penalties would be harsh enough in discouragement of taking the deduction. ”
