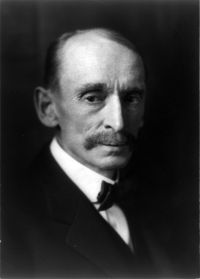
 William R. Day,
Williams v. City of Talladega…
“ We have, then, an ordinance which taxes, without exemption, the privilege of carrying on a business a part of which is that of a governmental agency constituted under a law of the United States and engaged in an essential part of the public business, communication between the officers and departments of the Federal government. The ordinance, making no exception of this class of business, necessarily includes its transaction within the privilege tax levied. This part of the license exacted necessarily affects the whole, and makes the tax unconstitutional and void. ”
