Summary

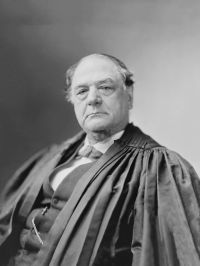
Portrait of Noah Haynes Swayne Noah Haynes Swayne Home Insurance Company v. City Council of Augusta…

There is no difference in principle between such a tax and those which have been paid by the plaintiff in error to the defendant in error, and to the State, without objection.
In the ordinance in question the tax is designated 'a license tax,' but its payment is not made a condition precedent to the right to do business. No special penalty is prescribed for its non-payment, and no second license is required to be taken out. Had the ordinance been otherwise in these particulars, we have seen, viewing the subject in the light of the License Tax Cases, that the result would have been the same.
Source: Wikisource

Portrait of Noah Haynes Swayne Noah Haynes Swayne Home Insurance Company v. City Council of Augusta…

A general law of the State imposed a tax of one per cent upon the gross amount of premiums received. An ordinance of the city imposed a tax of one and a quarter per cent upon such receipts. These taxes were paid by the company without objection. On the 5th of January, 1874, the city council passed an ordinance which imposed, further, a license tax of $250 'on each and every fire, marine, or accidental insurance company located, having an office, or doing business within the city of Augusta.' The bill was filed to enjoin the collection of this tax.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature