Summary

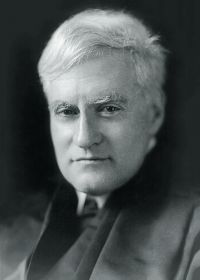
Portrait of Benjamin N. Cardozo Benjamin N. Cardozo Woolford Realty Company v. Rose…

In the first place, an interpretation of net income, by which it is also a net loss, involves the reading of the words of the statute in a strained and unnatural sense. The metamorphosis is too great to be viewed without a shock. Certainly the average man suffering a net loss from the operations of his business would learn with surprise that, within the meaning of the Congress, the amount of his net loss was also the amount of his net income.
Source: Wikisource

Portrait of Benjamin N. Cardozo Benjamin N. Cardozo Woolford Realty Company v. Rose…

If the loss for the first year is more than the income for the second, the excess is to be carried over to a third year, and deducted from the net income, if any, returnable for that year, at which time the process of carrying over is to end. Cf. Report of Senate Committee in charge of the Revenue Act of 1924, Senate Report No. 398, 68th Congress, 1st Session, p. 20. Obviously, the direction to apply the excess against the income of a later year is inconsistent with a purpose to allow it to an affiliated company as an immediate deduction from income of the current year.
Source: Wikisource

Portrait of Benjamin N. Cardozo Benjamin N. Cardozo Woolford Realty Company v. Rose…

The petitioner would have us hold that the minus quantities for all the years should be added together, and the total turned over by the company suffering the loss as an allowance to be made to the company realizing the gain. In that view of the statute, a net loss for a taxable year becomes, for the purpose of determining the burdens of affiliated corporations, though not for any other, the equivalent of a net income, and deductions which the statute has said shall be made only from net income may, none the less, by some process of legerdemain, be subtracted from the loss.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature