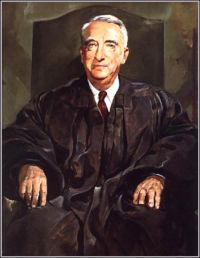
 Fred M. Vinson,
Reo Motors v. Commissioner of Internal Revenue…
“ And, as in this case, what was no net operating loss at all for the year when the event occurred becomes a loss for that year through subsequent changes in the statutes. Similarly, in some cases in which the taxpayer had net income for the year under controlling law, subsequent changes in the law might produce a net operating loss for that year if petitioner's construction of the statute prevailed. We find no warrant for the view that Congress intended that a statute designed to equalize tax burdens should be used to produce net losses where none had previously existed. ”
