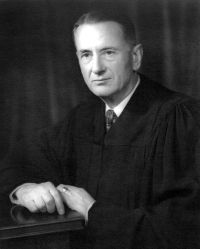
 Charles Evans Whittaker,
Bulova Watch Company v. United States…
“ Its argument would mean-in fact, it frankly proceeds on the theory-that a taxpayer, holding a refund claim attributable to an unused excess profits credit, could, by proceeding in a District Court or the Court of Claims, recover interest from the date when a claim for refund could have been filed, yet if he proceeded through the Tax Court he could not recover interest for any period prior to the actual filing of his claim, even though the Tax Court's final judgments (or orders) are subject to review by the United States Courts of Appeals and ultimately by this Court. ”
