Summary

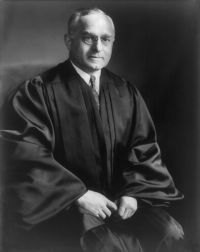
Portrait of Felix Frankfurter Felix Frankfurter Rosenman v. United States — Opinion of the Court

Claims for tax refunds must conform strictly to the requirements of Congress. A claim for refund of an estate tax 'alleged to have been erroneously or illegally assessed or collected must be presented to the Commissioner within three years next after the payment of such tax.' On the face of it, this requirement is couched in ordinary English, and since no extraneous relevant aids to construction have been called to our attention, Congress has evidently meant what these words ordinarily convey.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Rosenman v. United States — Opinion of the Court

No appeal to the Board of Tax Appeals having been taken, a deficiency of $48,534.84 was assessed. The Collector thereupon applied the balance of $39,775.76 standing to the credit of petitioners in the suspense account in partial satisfaction of this deficiency, and on April 22, 1938, petitioners paid to the Collector the additional amount of $10,497.34, which covered the remainder of the deficiency plus interest. The Commissioner then rejected the petitioners' claim for refund filed in March of that year.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature