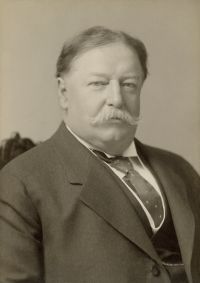
 William Howard Taft,
Girard Trust Company v. United States…
“ The government's contention is that the distinction made in section 1324, by which the interest to be paid on refunded taxes is to date from the payment of the taxes in cases where there is a specific protest setting forth in detail the basis and reasons for such protest, and by which the interest is to be dated only from six months after the date of filing the claim for refund or credit when there is no protest, was intended to favor those who furnished to the collecting officers by way of specific protest a valid basis for a refund of the taxes. ”
