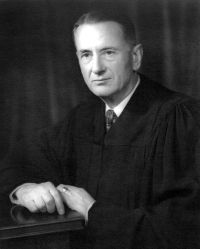
 Charles Evans Whittaker,
Commissioner of Internal Revenue v…
“ We turn, first, to the taxpayers' contention that, in substance, the purchaser, not the dealer, obtains the loan directly from a finance company, and that the percentage of the loan which is retained by the finance company-although credited on its books to a reserve account in the name of the dealer as collateral security for the payment of his liabilities to the finance company-is the property of the purchaser of the vehicle, not the dealer, and therefore may not be regarded as accrued income to the dealer. ”
