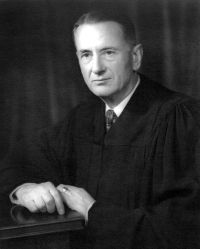
 Charles Evans Whittaker,
James v. United States (366 U.S. 213…
“ Since any consideration which may have passed is not legally recoverable, its recipient has realized a taxable gain, an 'accession to in come,' as clearly as if his 'indebtedness' had been descharged by a full release or by the running of a Statute of Limitations. As we have already shown at length, quite the opposite is true when an embezzlement occurs; for then the victim acquires an immediately ripe and enforceable claim to repayment, and the embezzler assumes a legal debt equal to his acquisition. ”
