Summary

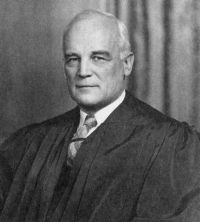
Portrait of Harold Hitz Burton Harold Hitz Burton Commissioner of Internal Revenue v…

Congress could have excluded from the gross income of all taxpayers the gains derived by debtors either from their acquisitions of their own obligations at a discount and their consequent control over them, or from their respective releases from all or part of such obligations by their respective creditors upon the debtor's payment to the creditor of something less than the full amount of the debt.
Source: Wikisource

Portrait of Harold Hitz Burton Harold Hitz Burton Commissioner of Internal Revenue v…

It is conceivable, although hardly likely, that a bondholder, in the ordinary course of business and without any express release of his debtor, might have sold part of his claims on the bonds he held at the full face value of those parts and then have made a gift of the rest of his claims on those bonds to the same debtor 'for nothing.' It is that kind of extraordinary transaction that the respondent asks us, as a matter of law, to read into the simple sales which actually took place and from which he derived financial gains.
Source: Wikisource

Portrait of Harold Hitz Burton Harold Hitz Burton Commissioner of Internal Revenue v…

The Tax Court's findings describe each bond sale that is material. Some were to the respondent personally and some to his law partner, acting on his behalf. The rest were made indirectly to the respondent through brokers or through the bondholders' committee. The Tax Court said that each sale that was made through a broker or the committee was closely akin to an open market transaction. It made no finding that any seller intended to transfer or release something for nothing. It referred to all of the respondent's acquisitions of bonds as purchases.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature