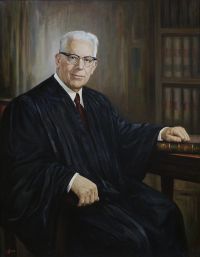
 Earl Warren,
Arnold v. Ben Kanowsky, Inc. — Opinion of the Court
“ These sales indisputably were made with the expectation that the parts would be incorporated in aircraft and that the aircraft would be sold. Such transactions are clearly within the concept of resale. [10] Since respondent has not sustained its burden of proving that 75% of its annual sales volume is not for resale and is recognized as being retail in the particular industry, we need not reach the question whether the additional standards of § 13 (a) (4) itself are met. [11] We hold that respondent has not satisfied the requirements of § 13 and is not entitled to exemption thereunder. ”
