Summary

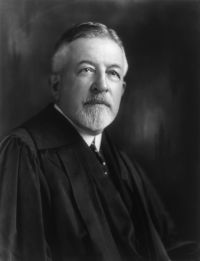
Portrait of Edward Terry Sanford Edward Terry Sanford Botany Worsted Mills v. United States…

And, on the contrary, it is stated that-'Before and since the date of the alleged settlement in this case Congress has evidently proceeded on the theory that no adjustment of a tax controversy between representatives of the Bureau of Internal Revenue and a taxpayer is binding unless made with the formalities and with the approval of the officials prescribed by statute. The authority of officers of the United States to compromise claims on behalf of or against the United States is strictly limited.
Source: Wikisource

Portrait of Edward Terry Sanford Edward Terry Sanford Botany Worsted Mills v. United States…

Where the Court of Claims does not make a finding upon the ultimate question of fact upon which the rights of the parties depend, but merely makes findings as to subsidiary circumstantial facts which bear upon it, such findings will not support a judgment unless the circumstantial facts as found are such that the ultimate fact follows from them as a necessary inference and may be held to result as a conclusion of law.
Source: Wikisource

Portrait of Edward Terry Sanford Edward Terry Sanford Botany Worsted Mills v. United States…

By section 12 (a) of the Revenue Act it was provided that in ascertaining the net income of a corporation organized in the United States, there should be deducted from its gross income all 'the ordinary and necessary expenses paid within the year in the maintenance and operation of its business and properties.' Under this provision the Mills deducted amounts aggregating $1,565,739.39 paid as compensation to the members of its board of directors, in addition to salaries of $9,000 each. It paid an income tax computed in accordance with this return.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature