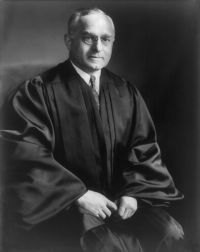
 Felix Frankfurter,
Angelus Milling Company v. Commissioner of Internal Revenue…
“ If the Commissioner chooses not to stand on his own formal or detailed requirements, it would be making an empty abstraction, and not a practical safeguard, of a regulation to allow the Commissioner to invoke technical objections after he has investigated the merits of a claim and taken action upon it. Even tax administration does not as a matter of principle preclude considerations of fairness.Since, however, the tight net which the Treasury Regulations fashion is for the protection of the revenue, courts should not unduly help disobedient refund claimants to slip through it. ”
