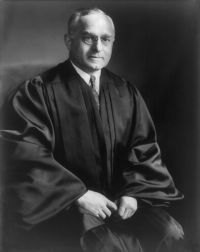
 Felix Frankfurter,
Braniff Airways v. Nebraska State Board of Equalization and Assessment…
“ The exercise of the taxing power by one of the States by means of a formula, based on such criteria as tonnage, revenue, and arrivals and departures, may, in isolation, impose no unfair burden on commerce. And the adoption by all the States of such a basis for taxation, which only congressional action could ensure, would not offend the Commerce Clause. It is the diverse and fluctuating exercise of power by the various States, even where based on concededly relevant factors, which imposes an undue burden on interstate commerce. ”
