Summary

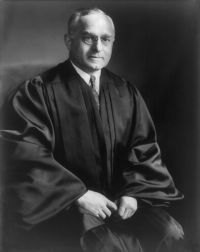
Portrait of Felix Frankfurter Felix Frankfurter Offutt Housing Company v. County of Sarpy…

The Government may have 'title,' but only a paper title, and, while it retained the controls described in the lease as a regulatory mechanism to prevent the ordinary operation of unbridled economic forces, this does not mean that the value of the buildings and improvements should thereby be partially allocated to it. If an ordinary private housing venture were being assessed for tax purposes, the value would not be allocated between an owner and the mortgage company which does his financing or between the owner and the State, which may fix rents and provide services.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Offutt Housing Company v. County of Sarpy…

Charged as we are with this function, we have concluded that the more persuasive construction of the statute, however flickering and feeble the light afforded for extracting its meaning, is that the States were to be permitted to tax private interests, like those of this petitioner, in housing projects located on areas subject to the federal power of 'exclusive Legislation.' We do not hold that Congress has relinquished this power over these areas. We hold only that Congress, in the exercise of this power, has permitted such state taxation as is involved in the present case.
Source: Wikisource

Portrait of Felix Frankfurter Felix Frankfurter Offutt Housing Company v. County of Sarpy…

The controlling facts are not in dispute. Petitioner is a Nebraska corporation organized primarily to provide housing for rent or sale. On January 18, 1951, petitioner entered into a contract with the Secretary of the Air Force to lease 63 acres of land and to build a housing project on Offutt Air Force Base in respondent county in accordance with specifications submitted to the Department of the Air Force and to be approved by the Federal Housing Commissioner.
Source: Wikisource

Get perspective with Kwize: daily news enlightened by great literature